Utah · Idaho · Colorado · Iowa
Stay in your home. Stop worrying about the monthly payment.
If you're 62 or older, the equity in your home can pay off your mortgage and give you breathing room again. We'll explain how in plain English — and tell you when a reverse mortgage isn't the right answer.
- You keep the title to your home
- No monthly mortgage payment required
- FHA-insured, non-recourse protection for your children
You did everything right. Retirement still feels tight.
Most of the people we talk to are not in trouble. They're careful, they own a good home, and they're tired of the same quiet math every month.
- A mortgage payment is eating a retirement income that stopped growing years ago.
- Savings are shrinking faster than expected, and care costs are only going up.
- The kids worry, the conversation gets awkward, and nobody wants to bring up selling.
It shouldn't take selling your home to enjoy what your home is worth.
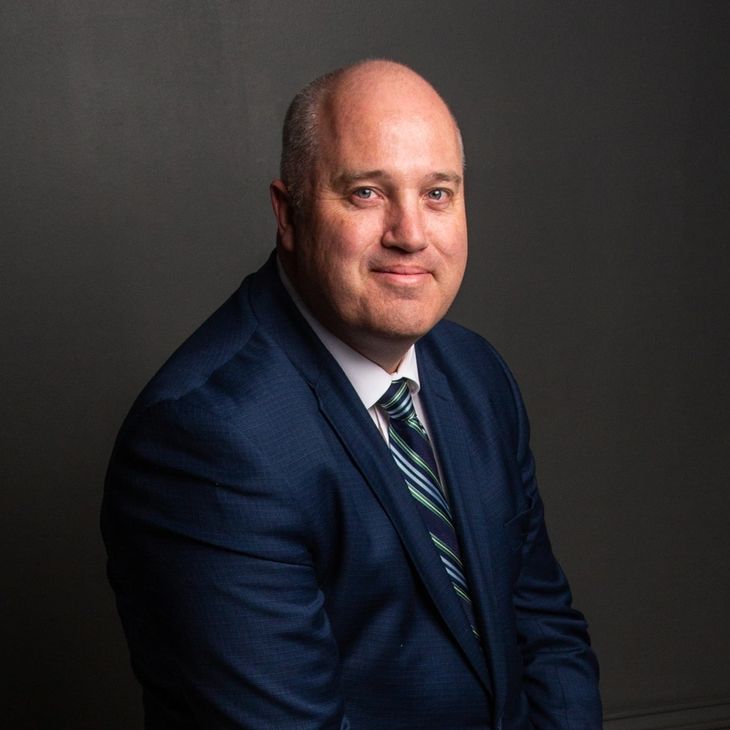
You don't need another salesperson
You need someone who has sat at this kitchen table a hundred times.
I've spent my career helping homeowners 62 and older make one decision carefully. No call center, no script, no handoff to a stranger. You get me on the phone, and you get the same answer I'd give my own parents — including "not yet" or "not at all" when that's the truth.
- One person, start to finish — you always reach the same voice
- Your family gets the full picture, not a sales pitch
- If it isn't right for you, we say so — and it costs you nothing
Three simple steps to a clear answer
Nothing happens fast, nothing happens without you, and nothing costs you a dollar until you decide to move forward.
1. Have one honest call
Twenty minutes on the phone. You tell us what you're facing; we tell you whether a reverse mortgage helps — including when it doesn't.
2. See your real numbers
A personal illustration: what you'd qualify for, every cost, and how the balance grows. Bring your kids to the review.
3. Decide with confidence
HUD counseling, then closing in 30–45 days. Or you walk away with clarity and no bill.
What's actually at stake
If nothing changes
- • Keep making a payment your income can't comfortably carry
- • Spend down the savings meant for care and emergencies
- • Sell the home you raised your family in, on someone else's timeline
- • Let your children quietly cover the gaps
After one clear conversation
- The monthly mortgage payment goes away
- A growing line of credit sits there for whatever comes
- You stay in your home, with the title still in your name
- Your family stops guessing and starts planning with you
The four questions everyone asks first
Do I lose my home?
No. You keep the title, exactly as you do now. A reverse mortgage is a loan against the house — the lender never owns it. Live there, keep up taxes, insurance and upkeep, and it stays yours.
Will my children inherit debt?
Never. HECM loans are federally insured and non-recourse. If the balance ever exceeds what the home sells for, FHA insurance covers the difference — not your heirs. Any remaining equity is theirs.
Is this a last resort for people in trouble?
Not anymore. Financial planners routinely use the reverse mortgage line of credit as a strategy — to delay Social Security, ride out down markets, or fund in-home care instead of a facility.
What if it isn't right for me?
Then we say so on the first call and you owe us nothing. We only do reverse mortgages, so we have no reason to steer you into one that doesn't make you better off.
People who were exactly where you are
Every one of these conversations started the same way — a phone call, a few questions, and a family that wanted the truth before anything else.
We were pulling $1,900 out of savings every month just to cover the mortgage. Now that payment is gone and the savings stay put. I wish we'd called two years earlier.
I was the skeptical daughter. He walked my mom and me through the whole thing, showed us the numbers, and answered the inheritance question before I could ask it.
He told me on the first call that waiting a year would give me a better number. Who does that? When it was time, he was the only person I called.
One call. A straight answer. Nothing to sign.
Tell us about your home and your goals. We'll show you the real numbers and tell you whether a reverse mortgage makes you better off — or whether it doesn't.